







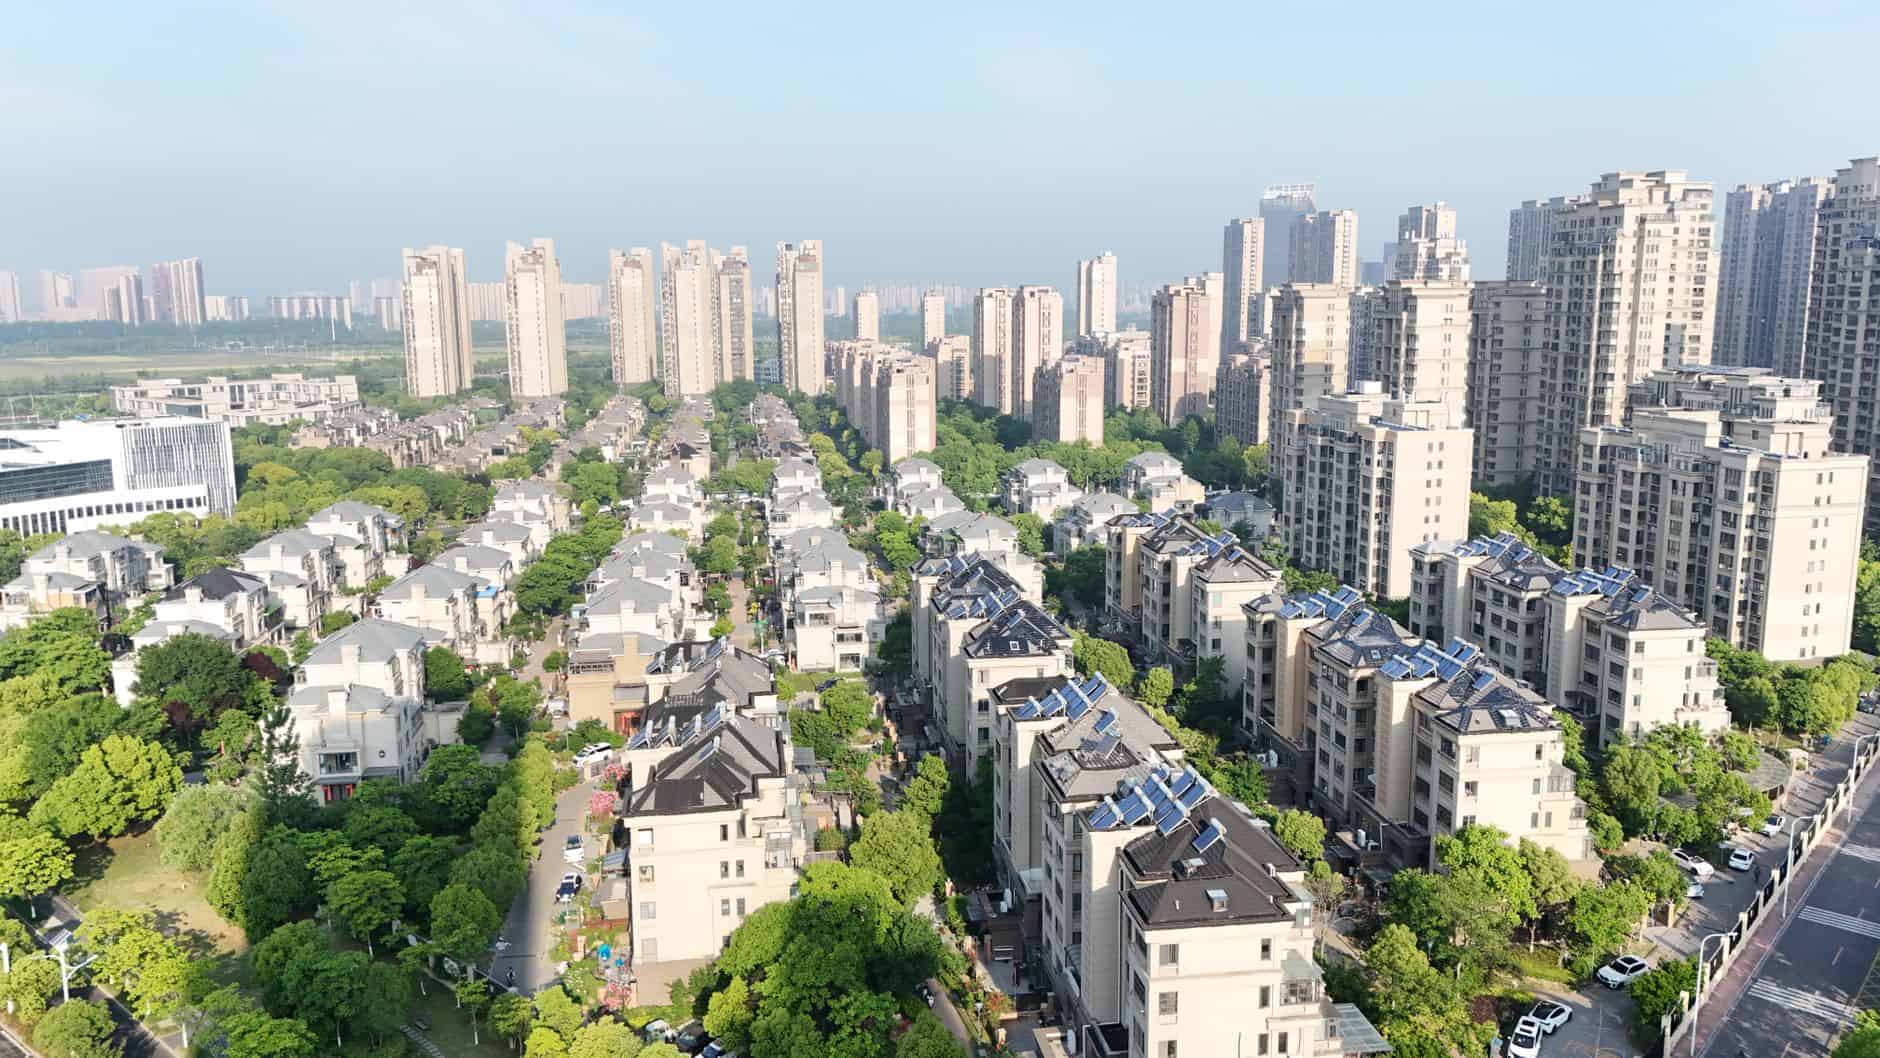
Understanding Solar Investment Carried Interest: Structure, Tax Implications, and Legal Considerations for Renewable Energy Investors
The Role of Carried Interest in Solar Investment Structures
Carried interest serves as a fundamental component within the investment structure of renewable energy funds, particularly those focused on solar investment. It represents the percentage of profit allocated to fund managers as a performance fee, incentivizing the optimization of project returns. This model is predominantly used by private equity firms overseeing solar projects to align the financial objectives of fund managers and limited partners.
Industry standards place carried interest rates in the range of 15% to 25%, with approximately 20% being typical among renewable energy funds. This rate reflects standard practice in private equity firms managing solar assets, where performance-based compensation motivates active management to enhance project efficiency and returns.
The investment structure ensures that fund managers receive carried interest only after limited partners have obtained their capital commitments plus preferred returns. This sequence prioritizes risk mitigation for limited partners while granting fund managers a meaningful share of upside profits. Such contractual agreements create a framework in which collaboration between capital providers and operational managers is integral to successful solar project delivery.
Mechanisms for Calculating Carried Interest in Solar Projects
Carried interest calculations within solar projects rely on detailed financial modeling that captures the investment horizon and unique cash flow dynamics of renewable energy funds. Central to this process are distribution waterfalls, which define the priority and conditions of profit allocation among limited partners and fund managers.
Solar investment funds typically enforce an 8% preferred return hurdle rate on capital commitments from limited partners before carried interest applies. Once this hurdle is achieved, the fund manager’s share “catches up” until the carried interest percentage—usually 20%—is fully realized. This tiered waterfall approach ensures limited partners recover a minimum return prior to management incentivization.
Financial modeling for a 10 MW solar plant within such funds includes projecting a 15–25 year investment horizon, encompassing:
- Initial capital expenditures for equipment and installation.
- Operational and maintenance costs throughout the plant’s lifespan.
- Revenue streams based on power purchase agreements (PPAs) or feed-in tariffs, noting these tariffs are subject to local regulatory updates and policy shifts.
Key factors in the carried interest calculation mechanisms include:
- Capital commitment: The principal amount invested by limited partners defines the base for return calculations.
- Preferred returns: Typically an annual rate set at or near 8%, ensuring limited partners recover priority returns before performance fees accrue.
- Catch-up provisions: Allow fund managers to receive a disproportionate share of subsequent profits up to the carried interest percentage after hurdle satisfaction.
- Residual distribution: Remaining profits after preferred returns and carried interest are split according to pre-agreed equity stakes.
The complexity of these models reflects the need to balance investment risks and incentives while maintaining transparent financial modeling consistent with the solar sector’s growth trajectory.
Tax Treatment and Regulatory Framework Governing Carried Interest in Solar Investments
The tax treatment of carried interest remains a critical factor influencing net investment returns for both fund managers and limited partners in renewable energy vehicles. Under current IRS guidelines effective as of 2026, carried interest is generally taxed as long-term capital gains rather than ordinary income, subjecting it to lower rates on the premise of a minimum holding period of three years established by recent tax reforms.
This tax classification improves the return on investment by reducing the effective tax burden on performance fees, though the specifics vary by jurisdiction and remain under legislative review. Funds with cross-border structures, such as Solar Plus Garden’s model employing an Estonian OÜ owning the solar asset and a Serbian DOO managing agrivoltaic community activities, must comply with tax laws and compliance requirements in both countries.
Key tax considerations include:
- The applicability of capital gains tax to profit components paid as carried interest, subject to local tax rules and international treaties.
- Potential differences in classification of carried interest between tax authorities, affecting tax rates and reporting obligations.
- Cross-border tax treaties that mitigate double taxation risks and safeguard investor interests.
Solar Plus Garden’s separation of ownership and operations within two legal entities provides a clear framework for tax reporting and compliance, minimizing regulatory uncertainties tied to carried interest distributions.
Impact of Carried Interest on Investor Returns and Fund Performance in the Solar Sector
The presence of carried interest directly influences the distribution of investment returns to limited partners by deducting a portion of profits as performance fees for fund managers. In multi-phase 10 MW solar projects managed by private equity firms, a carried interest rate between 15% and 25% commonly affects the net yield available to investors.
Within the solar sector, carried interest aligns инвестициона стратегија and operational focus among fund managers by equating compensation with fund performance. Limited partners maintain priority through preferred returns and capital preservation clauses, ensuring downside protection while sharing in project upside.
Empirical data from renewable energy funds indicates that despite these fees, total returns remain competitive, driven by steady cash flows from PPAs, government incentives, and increasing market demand for clean energy. Key elements contributing to positive fund performance include:
- Equity stakes structured to balance control and profit sharing.
- Robust financial modeling forecasting project cash flows over a 15–25 year lifespan.
- Proactive management of operational risks such as equipment downtime and regulatory compliance to safeguard revenue streams.
For limited partners, incorporating the effect of carried interest into return expectations is essential for accurate portfolio planning and risk assessment.
Legal and Compliance Risks Unique to Carried Interest in Solar Investment Funds
Carried interest agreements involve complex legal considerations that demand systematic risk management to prevent conflicts of interest and ensure fiduciary responsibility. Fund managers’ access to decision-making authority requires transparent contractual terms defining profit sharing, performance hurdles, and distribution mechanics.
In cross-jurisdictional projects such as those involving Estonia and Serbia, regulatory compliance encompasses tax filings, reporting accuracy, and adherence to evolving tax regulations и regulatory updates. Non-compliance risks include financial penalties and reputational damage.
Risk factors associated with carried interest structures include:
- Conflicts of interest where fund managers may prioritize short-term performance to enhance carried interest at the expense of the principal.
- Misinterpretation or inconsistent application of tax laws leading to non-compliance with IRS guidelines or local authorities.
- Disputes arising from ambiguous definitions in contractual agreements concerning distribution waterfalls or fee calculations.
Mitigation approaches involve:
- Detailed contractual provisions explicitly outlining carried interest calculation methodology, payment triggers, and dispute resolution processes.
- Independent external audits with transparent investor reporting to verify adherence to agreed terms.
- Ongoing legal reviews aligned with EU and local frameworks to anticipate changes and enforce compliance.
Empirical case studies confirm that rigorous legal frameworks correspond with smoother investor relations and reduced litigation in solar investment funds.
Integrating Carried Interest Models with Solar Plus Garden’s Community and Membership Investment Approach
Solar Plus Garden employs a dual investment structure combining traditional solar investment with a чланство у заједници model. The carried interest model coexists with membership fees, allowing financial incentives for fund managers while supporting communal agrivoltaic initiatives.
The 10 MW solar installation is owned and operated by an Estonian OÜ, managing capital commitments, equity stakes, and related performance fees including carried interest to fund managers and limited partners. Separately, a Serbian DOO administers the Garden community membership, which funds community activities through membership fees disconnected from direct solar equity participation.
Financial flows are structured as follows:
- A one-time €200 membership fee grants access to the Garden community, providing participation without mandatory solar equity investment.
- An optional €20 per month Garden box subscription delivers 18 annual shipments of locally grown produce, integrating regenerative agriculture into the community experience.
- Solar-generated income, including distributed carried interest profits, fund community costs under a regulated escrow and payment model designed to avoid commingling and preserve transparency.
This separation and legal clarity satisfy compliance requirements and enable accurate financial modeling for both solar asset returns and community investments, supporting investor confidence and long-term sustainability.
Често постављана питања
How does carried interest affect my share of returns as a small solar investor?
Carried interest is the share of profits, generally around 20%, paid to fund managers as a performance fee. As a limited partner, your net investment returns are calculated after deducting carried interest and management fees. This aligns fund managers’ incentives with project profitability, ensuring they benefit primarily when returns exceed hurdle thresholds.
What tax advantages does carried interest offer in solar investments?
Currently, carried interest qualifies for taxation as long-term capital gains tax, which applies a lower rate than ordinary income tax under IRS guidelines and compatible international tax laws. This reduces the tax burden on fund managers’ performance fees, potentially enhancing overall fund performance and returns. However, these benefits depend on adherence to holding period requirements and remain subject to legislative changes.
Can I access the Garden community without directly investing in the solar project?
Yes, Solar Plus Garden allows access to the Garden community through a membership fee of €200. This fee is invested into solar projects but does not require direct equity participation in the solar asset or carried interest arrangements, enabling broader community involvement while maintaining transparent investment structures.
What legal safeguards ensure transparency in carried interest allocations at Solar Plus Garden?
Solar Plus Garden maintains legal separation between Estonian and Serbian entities, employs escrow accounts for secure fund management, and uses explicit contractual agreements specifying calculated profit-sharing and performance fee triggers. Independent audits and investor reporting further safeguard transparency and compliance with tax and financial regulations.
Закључак
Investors evaluating solar projects with carried interest components should assess the specific investment structure, tax implications, and ongoing regulatory updates relevant to renewable energy funds. Solar Plus Garden’s regulated framework and transparent financial model provide a foundation for informed decision-making aligned with long-term investment horizons typical for 10 MW solar plants.
Potential investors must consider how carried interest rates, tax treatment including capital gains tax prospects, and legal safeguards affect net returns and risk exposure. Monitoring changes in tax regulations and compliance requirements within the applicable jurisdictions remains essential. Prospective participants are encouraged to review contractual terms carefully and understand community membership roles alongside traditional solar equity investment.






