






Comprehensive Analysis of the Global Solar Market Size in 2026
Current Scale and Composition of the Global Solar Energy Market
As of the first quarter of 2026, the global solar energy market size is defined primarily by the installed solar fotovoltaïsch (PV) capacity, reaching over 1,200 gigawatts (GW) according to industry tracking databases such as IRENA and the International Energy Agency (IEA). The distribution of capacity shows a concentration in Asia-Pacific, which accounts for approximately 700 GW, predominantly in China with around 350 GW and India approximately 75 GW. Europe follows with close to 300 GW, heavily influenced by Germany’s 65 GW and Spain’s 25 GW, while North America holds about 150 GW, led by the United States with roughly 120 GW. Latin America, the Middle East, and Africa cumulatively contribute under 100 GW, with growth focused on Brazil and South Africa within this aggregation.
Regarding technology share within the global solar energy market, crystalline silicon panels dominate with over 90% of installed capacity. This is split approximately evenly between monocrystalline (higher efficiency, 20-24% module efficiency range) and polycrystalline (17-20% efficiency) panels. Thin-film technologies, including cadmium telluride (CdTe) and copper indium gallium selenide (CIGS), account for approximately 8-10% of global capacity. These films exhibit specific advantages for applications such as building-integrated photovoltaics (BIPV), where flexibility and diffuse light performance outweigh absolute efficiency.
The installed solar capacity segmentation by scale shows utility-scale projects at the forefront, responsible for about 65% of total capacity. These installations typically exceed 10 MW per site and integrate with transmission-level grids through high-voltage substations. Commercial-scale systems, such as corporate rooftop arrays and mid-size installations ranging between 100 kW and 10 MW, account for roughly 20%. Residential solar, usually below 10 kW per system, forms around 15% of global capacity, with growth being sensitive to national policies on net metering and grid access charges.
Regulatory Frameworks Impacting Market Growth and Size
De zonnemarkt in 2026 operates within a complex regulatory environment that varies considerably by region but consistently shapes market expansion and investment flows. Key policy instruments include feed-in tariffs (FiTs), renewable portfolio standards (RPS), investment tax credits (ITCs), and direct grants supporting solar project development.
Within the European Union, the EU Green Deal and amended Renewable Energy Directive (RED II) establish binding targets aiming for at least 45% renewable energy share by 2030. Member states are directed to expedite permitting processes, limiting administrative lead times to under six months for solar projects in most cases. The directive promotes community solar projects backed by unified licensing frameworks, providing a regulatory basis for community investment models such as Solar Plus Garden’s membership approach.
In the United States, the Inflation Reduction Act (IRA) of 2022, extended through 2026, enhances the federal ITC for both solar and solar-plus-storage systems up to 30%, with bonus credits for domestic manufacturing and low-income community projects. These policies improve project bankability by reducing upfront capital costs and supporting long-term investment security. State-level incentives remain diverse, ranging from production tax credits to progressive renewable portfolio standards which influence localized solar deployment rates.
Asia-Pacific regulatory arrangements vary by country. China maintains local content requirements under its 14th Five-Year Plan, mandating a minimum 70% domestic component usage for utility-scale solar through 2026. India’s National Solar Mission includes viability gap funding for utility-scale projects and accelerated grid interconnection procedures with a target of under 90 days approval timeframes. Meanwhile, permitting and grid connection fees fluctuate widely across regions, affecting project timelines and financing structures.
Market Segments Driving Global Solar Capacity Expansion
Growth in the solar energy market size is propelled by heterogeneous segments with distinct dynamics. Residential rooftop solar systems continue to expand at approximately 8-12% CAGR globally, influenced by hardware price declines averaging 5-7% annually, increasing electrification demand, and supportive net metering regimes in over 50 countries assessed by the IEA.
Utility-scale solar farms are the primary growth engine for new capacity additions, with annual expansions between 10-15% recorded from 2024 to 2026. These installations benefit from economies of scale, reduced levelized cost of electricity (LCOE) often below €30/MWh in key markets, and stable power purchase agreements (PPAs) with corporate and utility off-takers locking terms up to 15-20 years.
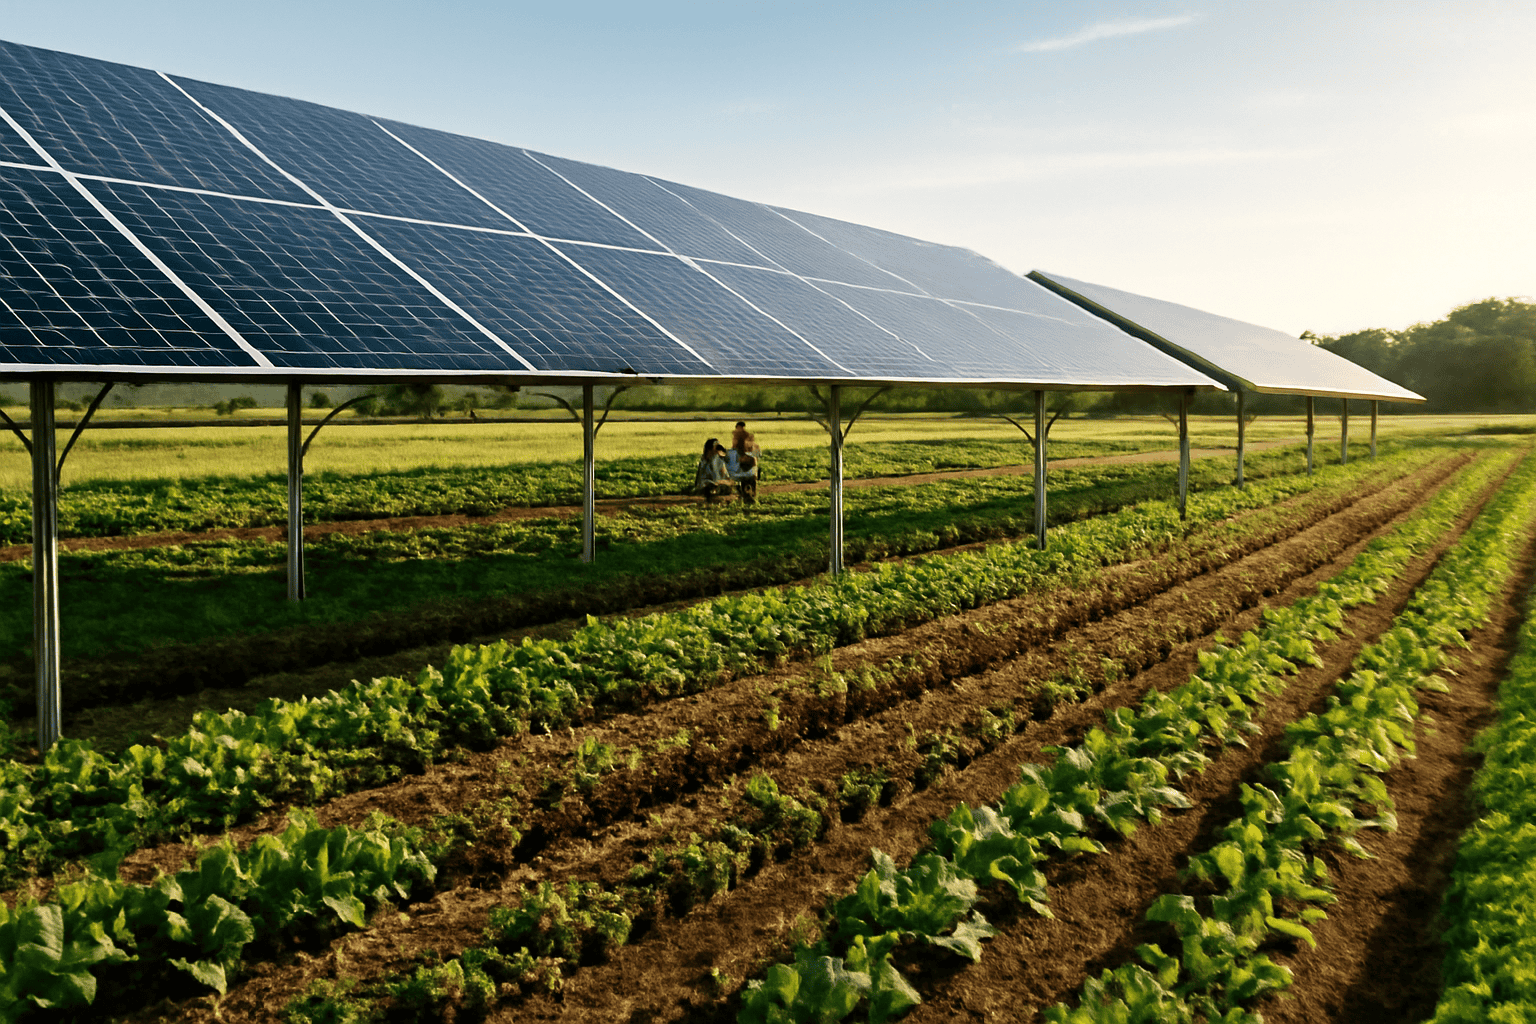
The emerging agrivoltaïcs segment integrates solar PV with agricultural production on the same land parcels. Industry estimates in 2026 attribute approximately 2-3% of new global solar capacity additions to agri-solar developments. This is supported by multifunctional land use optimization policies, especially in the EU’s Common Agricultural Policy framework, which provide financial incentives to combine crop production and solar PV installations, mitigating land competition and boosting rural development.
Decentralized solar-plus-storage configurations are gaining market share by offering grid deferral benefits and resiliency to end-users. Residential and commercial solar-plus-storage systems represent an estimated 15-20% of new deployments in industrialized countries, driven by declining lithium-ion battery costs (down roughly 80% since 2010) and supportive incentive schemes such as California’s Self-Generation Incentive Program (SGIP).
Technological Developments Affecting Solar Market Size and Efficiency
Technological progress maintains a critical role in shaping the global solar energy market by enhancing capacity utilization and lowering operational risks. Bifacial solar modules, capable of capturing irradiance on both front and rear sides, have seen adoption rates reach nearly 30% of newly installed utility-scale capacity in 2026. Yield improvements from bifacial technology range between 5-15%, contingent on ground albedo and panel height above ground.
Utility-scale solar farms increasingly employ single-axis trackers, which adjust panel tilt along a north-south axis, and dual-axis trackers that follow the sun’s azimuth and elevation. These tracking systems enhance solar exposure duration, producing yield increases estimated at 10-25% compared to fixed-tilt installations, depending on latitude and climate.
Advancements in inverter technology also impact market operational efficiency. Modern central and string inverters deliver peak conversion efficiencies exceeding 98%, incorporating grid support features such as voltage regulation, reactive power compensation, and low-voltage ride-through capabilities, critical for integrating high solar shares into weak or congested grids.
Module durability remains governed by industry standards such as IEC 61215 and IEC 61730, which stipulate mechanical and environmental performance. Leading manufacturers now offer performance warranties ensuring less than 0.5% degradation annually, securing more than 80% of original output after 25 years, which improves asset valuation and investor confidence.
Investment Patterns and Capital Flows in the 2026 Global Solar Market
De global solar energy market in 2026 exhibits diversified capital inflows from institutional investors, private equity firms, and innovative community-based investment structures. Annual global investment volume exceeds €150 billion, according to BloombergNEF data, with large utility projects capturing a majority iterative allocation from pension funds, sovereign wealth funds, and insurance companies prioritizing low-risk, stable-returns assets.
Community investment models typified by Solar Plus Garden integrate capital aggregation through a membership fee system. This approach finances a base 10 MW solar plant operated via an Estonian OÜ corporate entity, while a separate Serbian DOO manages garden community activities. The model operates under clearly defined escrow and payment control systems, preventing unregulated expenditure and ensuring all funds support the planned solar infrastructure and community operations. The lower investment entry point facilitates participation from smaller investors previously excluded from large-scale solar projects.
Financial instruments within the solar market have expanded beyond traditional equity to include green bonds, securitized loan products, and yield-cooperative models. Equity arrangements provide profit-sharing aligned with plant performance, while loan-based models offer fixed payout streams forecasted through detailed production modeling and PPA-backed revenue structures, allowing investors to match risk and return profiles with their financial objectives.
Market Outlook and Forecast for Global Solar Capacity Growth Through 2030
Research institutions including IEA’s World Energy Outlook and Wood Mackenzie forecast annual global solar capacity additions between 150 and 200 GW per year through 2030 under current policy trajectories. Cumulative installed capacity is projected to exceed 3,000 GW by the decade’s end, driven by enhanced national renewable energy targets and corporate commitments to decarbonization.
Expected continued module efficiency improvements, declining balance-of-system costs, and advances in grid integration will sustain downward pressure on the levelized cost of solar electricity. However, growth is subject to several supply chain and market constraints:
- Supply chain risks: Concentrations in polysilicon production primarily in China and Malaysia expose projects to potential bottlenecks with lead times stretching from raw material sourcing to wafer processing currently averaging four to six months.
- Raw material constraints: Critical metals such as silver, indium, and tellurium have exhibited price volatility due to soaring demand for PV and electronics; recycling initiatives and alternative materials research are being pursued to mitigate these pressures.
- Market saturation: In regions with solar penetration above 30% of electricity generation, grid stability concerns and curtailment (reductions of solar output to balance supply and demand) are rising, with curtailment rates reaching up to 5% as reported by independent system operators (ISOs) in certain EU countries.
Adaptive strategies, including diversified supply sourcing, circular economy principles, smart inverter deployment, and dynamic grid management techniques, are critical to maintaining resilient market expansion and realizing the global solar energy market size projections.
Regional Case Study: European Solar Market Growth and Integration Challenges
Europe’s solar market has surpassed 300 GW installed capacity in 2026, reflecting a compound annual growth rate of approximately 10% since 2020. Annual new capacity additions are approximately 20 GW, predominantly driven by Germany’s ongoing distributed solar growth and Spain’s surge in utility-scale solar park installations.
Grid integration challenges remain significant, especially for decentralized and community solar installations. Data from ENTSO-E for 2025 documents curtailment rates up to 5% in regions such as Southern Germany and parts of Spain, due to grid congestion and voltage regulation issues. Increased deployment of advanced inverters with grid-forming capabilities and demand response programs are mitigating some impacts.
Cross-border electricity trading leveraging the EU’s Internal Electricity Market facilitates optimization of solar power dispatch across member states with variable solar supply. This integration improves the economic viability of solar investments and supports community schemes such as Solar Plus Garden, promoting agrivoltaics and localized energy and food production within the same land use frameworks.
At the country level, Germany and Spain showcase mature distributed solar capacity with grid codes enabling streamlined connections for residential and commercial systems within 30-60 days. Conversely, Eastern European countries including Poland and Romania demonstrate rapid capacity growth but face infrastructural bottlenecks with grid upgrade lead times extending beyond 12 months.
Innovative Business Models Expanding Solar Energy Market Participation
Community-driven investment platforms represent a growing segment within the zonne-energie-industrie, integrating solar energy production with ancillary community activities such as agricultural initiatives and local food supply systems. Solar Plus Garden employs a dual-legal-entity framework: an Estonian OÜ owning and operating the core 10 MW solar installations, and a Serbian DOO managing the garden community operations and membership benefits.
The platform’s membership fee structure (for instance, a one-time fee of €200 and an optional €20/month tuinbak subscription) finances both the solar infrastructure and community activities, ensuring consistent funding streams underpinned by clear contractual and escrow protections. This legally distinct separation between solar asset ownership and community management underpins investor transparency and regulatory compliance across jurisdictions.
Such models open the global solar market to small and medium investors by lowering entry thresholds, providing structured governance, and limiting investment risk through defined cash flow controls. They also promote multifunctional land use and social engagement aligning with sustainability criteria increasingly demanded by stakeholders.
Veelgestelde vragen (FAQ)
- What is the current total installed global solar PV capacity as of 2026?
- As of early 2026, total global installed solar PV capacity has surpassed approximately 1,200 GW, with Asia-Pacific leading deployment primarily through China and India, followed by Europe and North America. This capacity spans utility-scale, commercial, and residential segments.
- How do regulatory policies affect the growth of the global solar market?
- Regulatory frameworks including feed-in tariffs, renewable energy targets, investment tax credits, and streamlined permitting processes directly influence project feasibility, financing, and deployment timelines. Policies such as the EU Green Deal and the U.S. Inflation Reduction Act serve as national and regional drivers for expansion and investor confidence.
- What distinguishes community-based solar investment models like Solar Plus Garden from traditional solar projects?
- Community solar investment models incorporate membership fees as ongoing funding mechanisms supporting both solar energy production and local community activities, such as agriculture, thereby diversifying revenue streams and enhancing governance via legally distinct entities. This structure enables participation from smaller investors and promotes sustainable long-term engagement.
- What are the significant risks that could constrain global solar market growth between 2026 and 2030?
- Key constraints include supply chain vulnerabilities in polysilicon and component manufacturing, raw material price volatility for silver and tellurium, regulatory policy changes, grid integration challenges including curtailment risks, and market saturation in highly penetrated regions. Robust mitigation strategies will be required to sustain projected growth.
Conclusie
Stakeholders assessing opportunities in the global solar energy market for 2026 and beyond should analyze the regional solar market size, regulatory frameworks, and technical segmentation across utility-scale, residential, and emerging sectors like agrivoltaics. Technological advancements such as bifacial modules and smart inverter technologies are crucial factors affecting system efficiency and asset valuation.
Innovative investment and community engagement models, including Solar Plus Garden’s membership-driven platform, expand market participation and reduce entry barriers for smaller investors. Despite optimistic capacity growth forecasts toward 2030, continuous monitoring of supply chain developments, evolving policy landscapes, and grid integration challenges is essential to maintaining competitive positioning and project viability within the global solar energy market as reported in current industry market reports.
Gerelateerde artikelen
- Uitgebreide prognoses voor de groei van de zonne-energiemarkt en inzichten in investeringen tot 2026.
- Investeringsmogelijkheden in zonneparken in 2026: een uitgebreide gids voor investeren in zonne-energie
- Investeer vandaag nog in zonne-energie: uw complete gids voor duurzame investeringen in hernieuwbare energie.






